Ohio Plumbing Installation Floater Insurance
9:00am - 5:00pm Mon-Fri
We'll Reply in 15min*
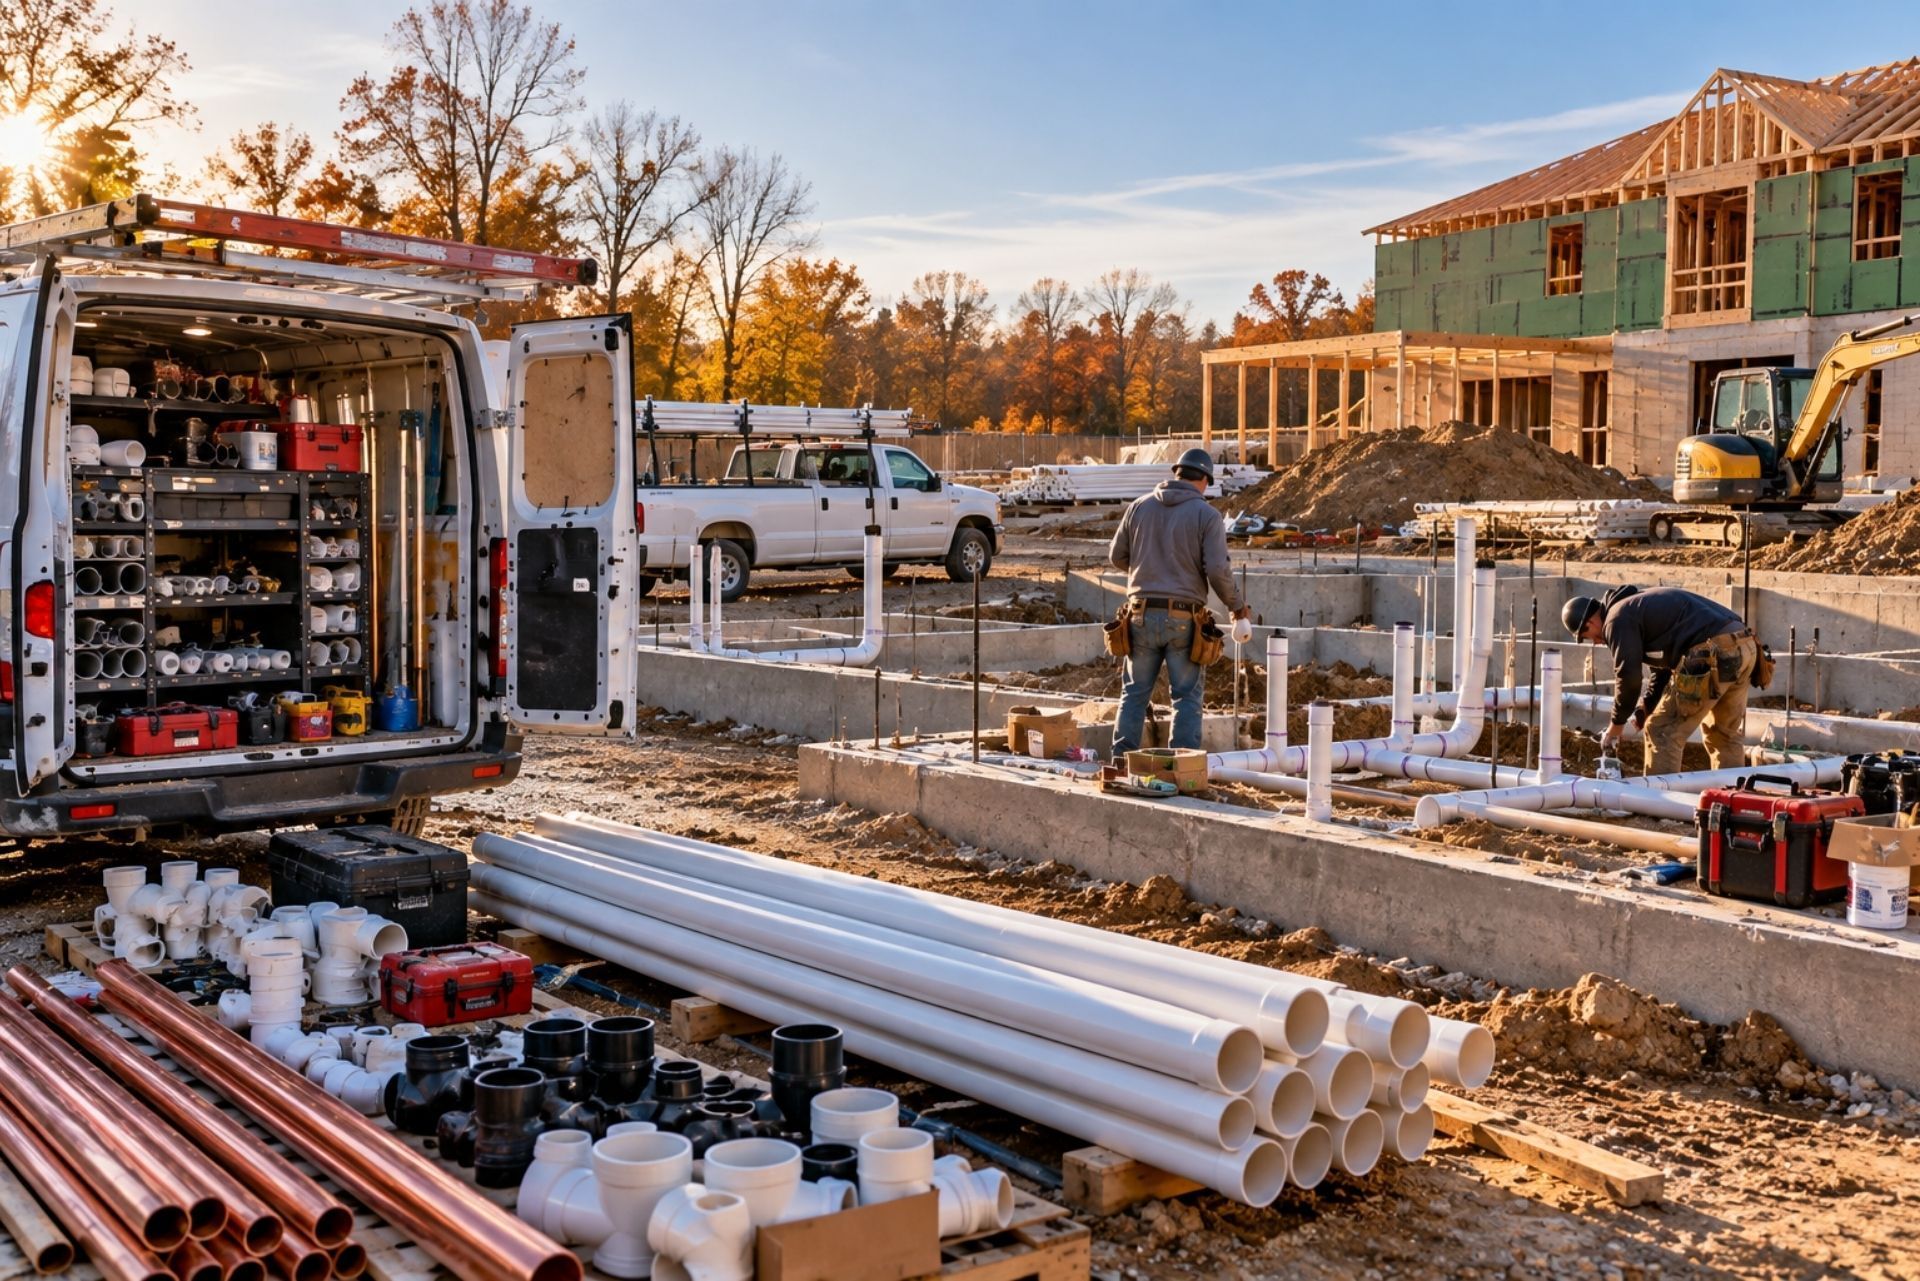
A single water heater replacement in Ohio can now run upward of $3,500 once you factor in code-mandated expansion tanks and mixing valves, a sharp jump from the $2,000 price tag that was common just two years ago. That rising per-fixture cost means plumbing contractors have more money sitting on job sites, in transit, and in storage than ever before. If those materials are stolen, vandalized, or damaged by weather before they're installed, your general liability policy won't cover the loss.
This is where a plumbing installation floater becomes essential. It's a specialized insurance product designed to protect fixtures,
pipes, fittings, and other materials from the moment you take ownership until they're permanently installed. For
Ohio contractors, understanding how this coverage works, what it excludes, and how it differs from other policies can mean the difference between absorbing a devastating loss and filing a straightforward claim. Whether you're running a two-person crew or managing multiple commercial projects, the right floater policy keeps your business financially protected at every stage of a job.
Understanding Installation Floaters for Ohio Plumbers
An installation floater is a type of inland marine insurance tailored specifically for contractors. It covers materials, equipment, and fixtures that you own or are responsible for while they're being transported to a job site, stored temporarily, or in the process of being installed. Once the materials become a permanent part of the structure, they typically fall under the property owner's coverage or your completed operations policy.
For Ohio plumbers, this distinction matters. The state's construction industry licensing board requires contractors to carry a minimum of $500,000 in liability coverage to maintain a license. But that liability policy protects against third-party injury or property damage claims, not the loss of your own materials. A floater fills that gap.
What an Installation Floater Covers
Most installation floater policies protect against a broad range of perils. The standard covered events include:
- Fire, lightning, and explosion
- Theft and attempted theft
- Vandalism and malicious mischief
- Windstorm, hail, and other weather events
- Vehicle collision during transit
- Water damage from burst pipes or flooding at a storage location
Coverage typically applies from the point of purchase or delivery through final installation. Some policies extend to materials stored at your shop or warehouse, while others are limited to the job site and transit.
Why Standard General Liability Isn't Enough
General liability insurance is designed to protect you if a customer trips over your toolbox or if a pipe you installed leaks and damages a homeowner's floor. It responds to claims from other people, not to your own property losses.
If someone breaks into your work van overnight and steals $8,000 worth of copper fittings and a tankless water heater, your GL policy won't pay for that. Your commercial auto policy might cover the van itself, but not its contents. Without a floater, that loss comes directly out of your operating budget.
By: Aaron McElwain
President of Bellwether Insurance
Key Risks for Plumbing Projects in Ohio
Ohio's geography and climate create a specific set of risks that plumbing contractors need to plan for. From organized theft rings targeting construction sites to severe spring storms, the threats to uninstalled materials are real and frequent.
Theft and Vandalism at Job Sites
Construction site theft is a persistent problem across Ohio, particularly in urban areas like Columbus, Cleveland, and Cincinnati. Copper pipe, brass fittings, and high-end fixtures are easy to resell, making plumbing materials a prime target. Job sites under renovation or new construction are especially vulnerable during evenings and weekends when no crew is present.
Vandalism is a related concern. Unsecured sites can attract trespassers who damage materials even without stealing them. A floater policy that covers both theft and vandalism ensures you aren't paying out of pocket to replace materials and restart work.
Transit Protection for Fixtures and Materials
Your materials face risk every time they move. A delivery truck involved in an accident, a load that shifts and breaks during transport, or a package left at the wrong address can all result in significant losses. Transit coverage within a floater policy protects materials from the supplier's dock to your job site.
This is particularly relevant for Ohio contractors who source specialty fixtures from out-of-state distributors. High-value items like commercial-grade water heaters, custom valve assemblies, and stainless steel fixtures may travel hundreds of miles before reaching your hands.
Damage from Severe Ohio Weather Events
Ohio experiences tornadoes, severe thunderstorms, heavy snowfall, and ice storms throughout the year. Materials stored on an open job site or in a temporary structure are vulnerable to wind, hail, and water damage. A floater policy with broad weather coverage protects against these events, which are particularly common during the spring and early summer construction season.
One claim we've seen repeatedly involves materials stored in a partially enclosed structure during a fast-moving storm. Drywall, PVC pipe, and fixture boxes can be ruined in minutes by wind-driven rain. Without floater coverage, the contractor absorbs the full replacement cost.
Comparing Installation Floaters vs. Inland Marine Insurance
These two terms are often used interchangeably, but there's an important distinction. Inland marine insurance is the broad category. An installation floater is one specific type of inland marine policy.
| Feature | Installation Floater | General Inland Marine |
|---|---|---|
| Covers materials in transit | Yes | Yes |
| Covers materials at job site | Yes | Varies |
| Covers installed-but-not-accepted work | Yes | Rarely |
| Covers tools and equipment | Sometimes (by endorsement) | Yes (contractor's equipment policy) |
| Ends when work is permanently installed | Yes | N/A |
| Best suited for | Project-specific material coverage | Broad mobile property coverage |
A contractor's tools and equipment floater, another type of inland marine policy, covers your owned tools and machinery. An installation floater specifically covers materials destined for installation in someone else's property. You may need both, depending on the scale of your operation.
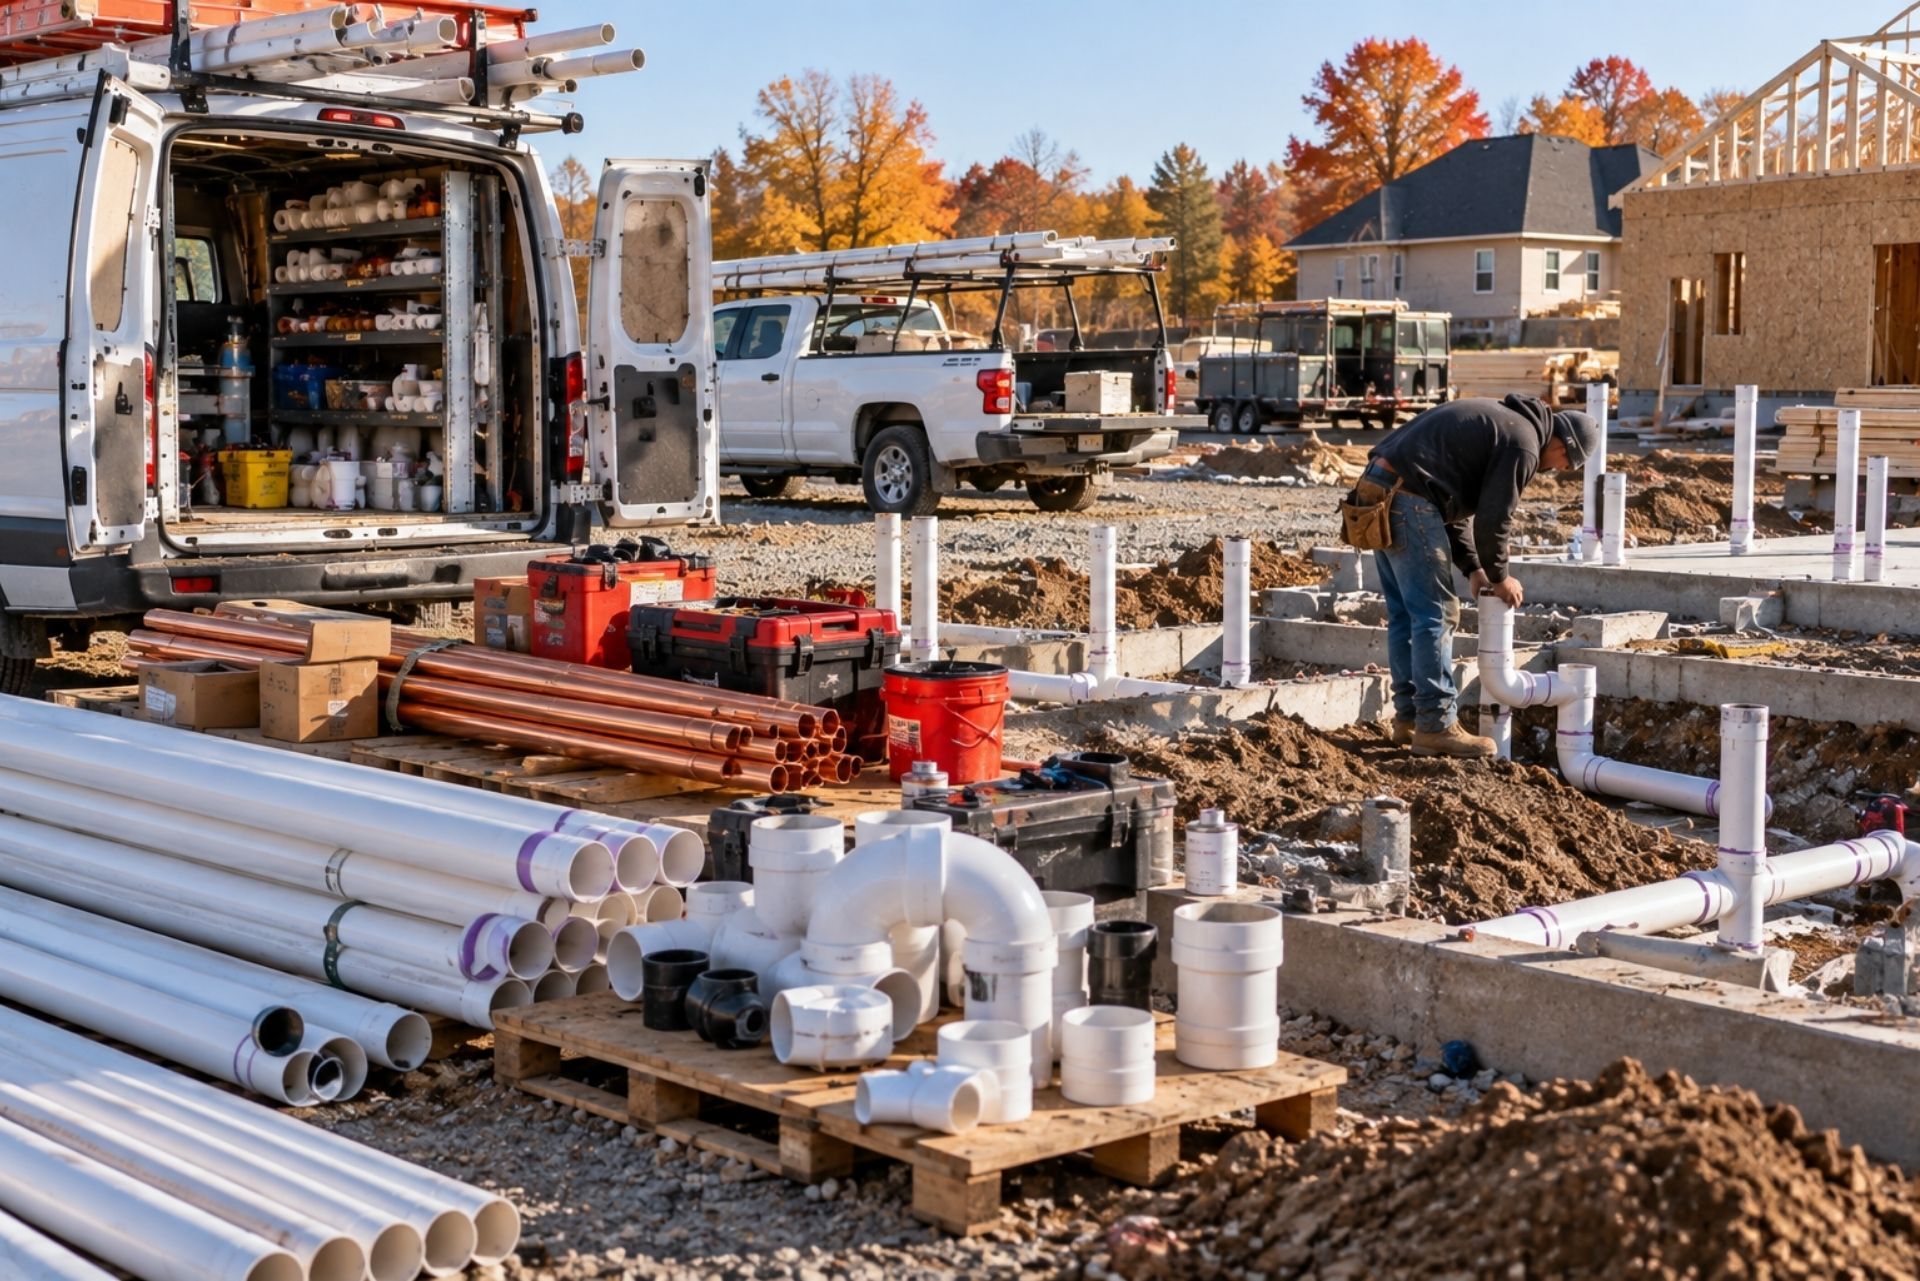
The key takeaway: if you're carrying $15,000 worth of fixtures to a commercial bathroom remodel, your tools policy won't cover those fixtures. You need an installation floater for that.
Determining Your Coverage Needs
Choosing the right coverage amount and policy structure depends on the size and nature of your projects. Underinsuring is one of the most common mistakes we see among Ohio plumbing contractors.
Total Project Values vs. Single Load Limits
Your policy should reflect the maximum value of materials you'll have exposed at any one time. This isn't the same as your total annual revenue. Consider the largest single project you might take on, then add a buffer for price fluctuations in materials.
Ohio's updated plumbing code, including 2025 amendments that mandate high-cost components like expansion tanks and thermostatic mixing valves, has pushed per-project material costs higher. A water heater installation that once required $200 in parts may now need $600 or more in additional code-required components. These costs add up quickly across a multi-unit project.
For contractors working on commercial properties, the math gets even more demanding. Ohio commercial property managers frequently require total liability limits between $3 million and $4 million from their subcontractors. Your floater limits should be proportional to the material values on these larger jobs.
Reporting Policies vs. Blanket Coverage
Two common policy structures exist for installation floaters:
- A reporting policy requires you to report the value of materials on each project as work begins. Your premium adjusts based on actual exposure. This works well for contractors with fluctuating project sizes.
- A blanket policy sets a fixed coverage limit for the entire policy period. You pay a flat premium regardless of how many projects you run. This is simpler to manage but may cost more if your project volume varies significantly.
Smaller plumbing operations often prefer blanket coverage for its simplicity. Larger firms with multiple active projects may benefit from reporting policies that more accurately reflect their actual risk.
Common Questions About Plumbing Floater Policies
Does my floater cover materials I haven't paid for yet? It depends on your contract terms. If you've taken delivery and are responsible for the materials, most floater policies will cover them regardless of payment status. Check your policy's "insurable interest" language.
Are fixtures covered once they're partially installed? Yes. Most installation floaters cover materials through the entire installation process until the work is accepted by the property owner or the project reaches substantial completion.
What's typically excluded from coverage? Common exclusions include damage from faulty workmanship, normal wear and tear, earthquake, flood (unless specifically endorsed), and materials left at an unsecured location without reasonable protective measures. Mysterious disappearance, where items go missing without evidence of theft, is also frequently excluded.
Do I need a separate policy for each project? Not usually. Most floater policies cover all your active projects within the policy period, up to your coverage limit. Project-specific policies exist but are more common for large commercial jobs.
How much does an installation floater cost in Ohio? Premiums vary based on your coverage limits, deductible, claims history, and the types of projects you handle. For most trades, including plumbing, inland marine premiums for installation floaters typically run between 1% and 3% of the total insured value (https://farmerbrown.com/business/general-contractors-insurance/excavation-contractors/). A $100,000 floater might cost between $1,000 and $3,000 per year (https://www.hvacinsure.com/multi-truck-hvac-business-insurance).
Will my floater cover materials stored at my shop?
Many policies include coverage for materials at a scheduled location like your warehouse or shop. You'll need to list these locations on your policy. Unscheduled storage locations may not be covered.
Making the Right Choice for Your Contracting Business
Plumbing installation floater insurance isn't optional for Ohio contractors who carry any meaningful inventory of fixtures and materials. The combination of rising material costs driven by code changes that have significantly increased per-fixture project values, persistent job site theft, and Ohio's unpredictable weather makes this coverage a core part of your risk management strategy.
Start by calculating the maximum value of materials you'd have exposed on your largest potential project. Talk to your insurance agent about whether a blanket or reporting policy fits your workflow better. Review exclusions carefully, especially around unsecured storage and mysterious disappearance, so you know exactly where your coverage ends.
If you're already carrying general liability and a tools floater, adding an installation floater rounds out your protection for the one asset category that's most vulnerable: materials that belong to you but haven't yet become part of someone else's building. Get quotes from at least two carriers, compare deductibles and exclusion lists side by side, and make sure your limits keep pace with the true cost of the materials you're installing in 2026.
About The Author:
Aaron McElwain, CIC
As President of Bellwether Insurance, I’m passionate about helping individuals and businesses protect what matters most through honest advice and reliable coverage. With my Certified Insurance Counselor (CIC) designation and years of industry experience, I focus on simplifying insurance, building lasting relationships, and delivering peace of mind through every policy we write.
OUR PERSONAL INSURANCE COVERAGE IN OHIO
Explore Personal Insurance Coverage in Ohio
We only work with outstanding insurance companies that offer great value and continually impress our clients.
Home Insurance
Protecting Ohio homes, ensuring comfort
Life Insurance
Safeguard futures, cherish moments
Umbrella Insurance
Extra coverage, ultimate peace
Car Insurance
On the road, confidently insured
Condo & Renters Insurance
Customized policies, worry-free living
Motorcycle Insurance
Ride fearlessly, enjoy the journey
Choose Bellwether Insurance Today for Personalized Protection
Get a Plan Tailored to Your Lifestyle
Bellwether Insurance evaluates the risks you and your family face, taking into account your assets, personal circumstances, and individual requirements to create a tailored insurance solution.
Recover with Confidence
With our personal insurance coverage, you'll be prepared to bounce back from unforeseen events that could have left you and your family in a difficult financial situation.
Avoid Overpaying
Through customized insurance plans, you'll receive adequate coverage without unnecessary costs. At Bellwether Insurance, we strive to keep premiums cost-effective while providing the protection you need.
Review from our Clients
Customer Testimonials
See why Ohio residents work with Bellwether Insurance Agency in LaGrange, Ohio


Arun K.
Personal Insurance Client
After a decade old relationship with a premium and commercial insurance provider.. my switch to Bellwether has left me wondering why I waited so long. Primarily my experience has been dealing with Jessica Fox.. and she's been awesome to work with. She's super responsive, stays on top to follow up on your enquiries and really gets things done to delight customers.

Rob J.
Personal Insurance Client
Absolute pleasure to work with. Sandra has taken care of all my insurance needs for over 2 years now. Bellwether was able to save me quite a bit of money over previous carrier. Always giving heads up on any changes, or weather it’s time to check for new price she’s on top of it. I recommend them often to friends and family.

Nick W.
Personal Insurance Client
Aaron and Sandra are amazing! I faithfully stayed with my previous insurance for over ten years until I had them review my policies. Wish I would have done it years ago. Saved me quite a bit of money as well as gaining coverage what's not to love? They respond very quickly and professionally. I work in sales as a profession so it's great to see that level of attention and attentiveness provided here. Stop your search and give them a shot you won't regret it. On a side note even though it is something so small I love the fact they send laminated copies of insurance cards anytime you make a change. 10/10

Bobby P.
Personal Insurance Client
Bellwether Insurance is the best ever! Always there when I need them and always has the answers with quick replies. I will never go with a different Insurance Agent. If I could, I would give then a 10 Star review! Thanks Sandra for all your help!